

Part 2: Finance Act of 2025 and other laws as at 31 March 2026
Relevant to those sitting TX-MYS in December 2026 or March 2027 and June 2027
Introduction
This is the second of two articles, provided by the TX-MYS examining team to update candidates on the legislation and related resources pertaining to taxation in Malaysia, covering areas in direct and indirect taxes which are included in the TX-MYS syllabus.
These articles should be read by candidates who are preparing for the TX-MYS exam in the period from 1 December 2026 to 30 June 2027.
Part 1 provides an overview of the main features of the Malaysian tax system covered in the TX-MYS syllabus as at 31 March 2026.
This Part 2 considers the changes brought about by:
- Finance Act 2025, Act 874, gazetted on 31 December 2025
- Measures for the Collection, Administration and Enforcement of Tax Act 2025, Act 875, gazetted on 31 December 2025, and
- Several gazette orders.
It should be noted that the subject matter of tax on gains or profits from the disposal of capital assets (capital gains), which was introduced in Act 851 but amended by the Income Tax (Amendment) Act 2024 and other amendments, will remain excluded from the TX-MYS syllabus for the exam year of December 2026 to June 2027. Given the exclusion, capital gains will not be discussed in detail beyond a cursory mention in these two articles.
Any reference to a section or schedule in this article refers to a provision of the Income Tax Act 1967 (as amended), unless otherwise specified.
The abbreviations used in this article are:
- CA – Capital Allowance
- CI – Chargeable Income
- DGIR – Director General of Inland Revenue
- EoT – Estimate of tax
- EPF – Employees’ Provident Fund
- FSI – Foreign-Sourced Income
- IHC – Investment Holding Company
- IRB – Inland Revenue Board
- LLP – Limited Liability Partnership
- MoF – Minister of Finance
- NR – Non-resident
- RPGT – Real Property Gains Tax
- SAS – Self-assessment system
- SSPN – National Education Savings Scheme
- w.e.f. – with effect from
- YA – Year of Assessment
Finance Act 2025 (Act 874) and Measures for the Collection, Administration and Enforcement of Tax Act 2025 (Act 875)
A. Overview
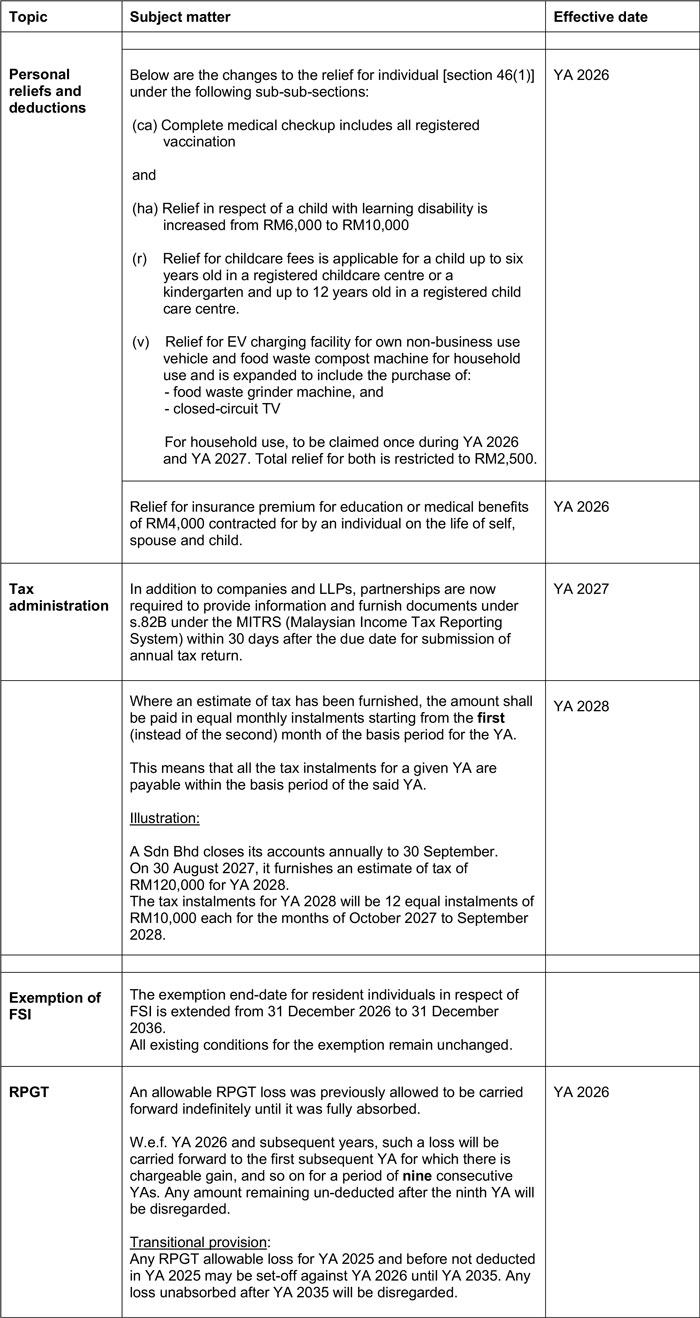
This Part presents an overview of the measures brought about by Budget 2026 as legislated in the Acts 874 and 875. It refers only the subject matter included in the TX-MYS syllabus and detailed study guide. Where deemed necessary, further discussion is followed-up in Part B.
Written by a member of the TX-MYS examining team
