

Part 2: Finance Act of 2025 and other laws as at 31 March 2026
Relevant to those sitting ATX-MYS in December 2026, March 2027 and June 2027
Introduction
This article is provided by the ATX-MYS examining team to update students on the legislation and related resources pertaining to advanced taxation in Malaysia, covering areas which are included in the ATX-MYS syllabus.
These articles should be read by students who are preparing for the ATX-MYS exam in the period from 1 December 2026 to 30 June 2027.
This article considers the changes brought about by:
- Finance Act 2025, Act 874, gazetted on 31 December 2025
- Measures for the Collection, Administration and Enforcement of Tax Act 2025, Act 875, gazetted on 31 December 2025, and
- Several gazette orders.
It should be noted that the subject matter of tax on gains or profits from the disposal of capital assets (capital gains), which was introduced in Act 851 and amended by the Income Tax (Amendment) Act 2024, is now included in the ATX-MYS syllabus for December 2026 and subsequent exams.
Any reference to a section or schedule in this article refers to a provision of the Income Tax Act 1967 (ITA), unless otherwise specified.
The abbreviations used in this article are:
- CI - Chargeable Income
- IRB - Inland Revenue Board
- LLP - Limited Liability Partnership
- NR - Non-resident
- PTF - Property Trust Fund
- REIT - Real Estate Investment Trust
- RPGT - Real Property Gains Tax
- SI - Statutory income
- w.e.f. - with effect from
- WHT - Withholding tax
- YA - Year of Assessment
Finance Act Act 2025 (Act 874) and Measures for the Collection, Administration and Enforcement of Tax Act 2025 (Act 875)
A. Overview
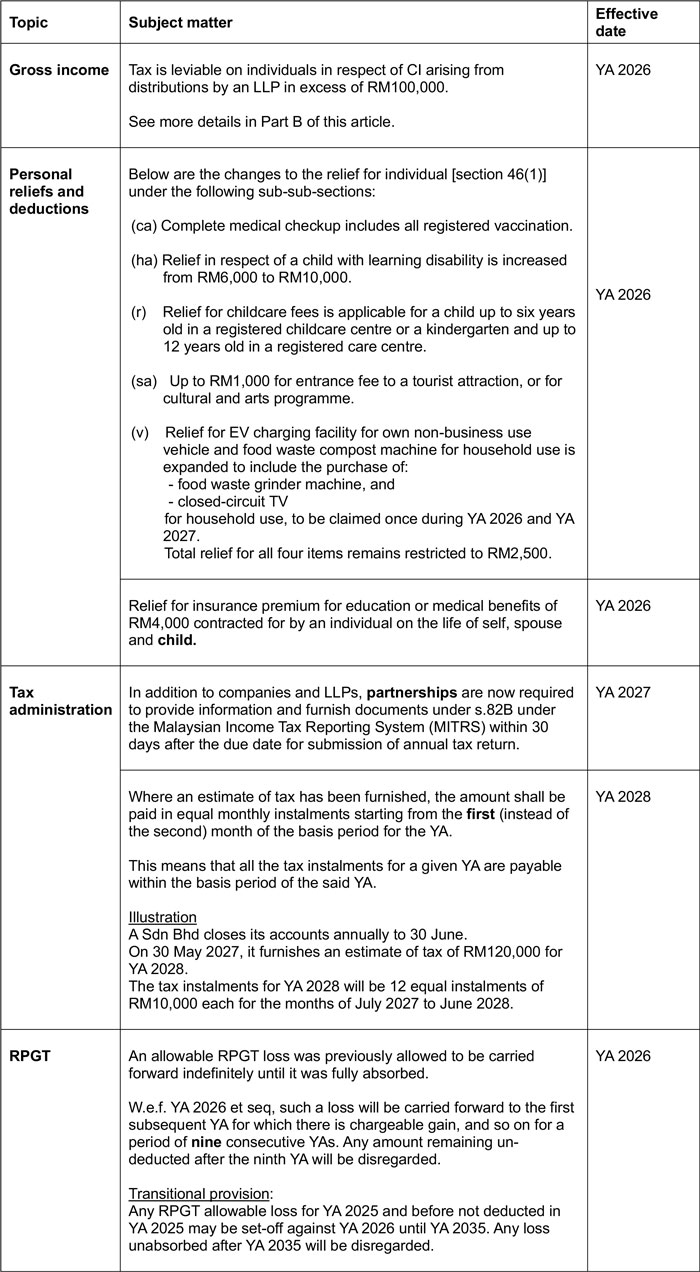
This Part presents an overview of the measures brought about by Budget 2026 as legislated in the Acts 874 and 875. It refers only to the subject matter included in the ATX-MYS syllabus and detailed study guide. Where deemed necessary, further discussion is followed up in Part B.
B. Further details
Discussed below in further details are some of the budget measures that directly relate to the areas of focus in the ATX-MYS syllabus.
1. Taxation of LLP distribution received by an individual
Up to and including YA 2025, any profit paid, credited or distributed, whether in cash or in kind, to a partner by an LLP, is tax exempt [paragraph 12C, Schedule 6, Income Tax Act 1967].
W.e.f. YA 2026, the LLP distribution to an individual, who may be resident or NR, is tax exempt only up to RM100,000 [paragraph 12D, Schedule 6, Income Tax Act 1967].
At the same time, a new provision [section 6(1)(s), Income Tax Act 1967] imposes income tax “… upon the income of an individual, who is a partner of an LLP, which consists of profits derived from Malaysia paid, credited or distributed, whether in cash or in kind, to the individual by the LLP at the appropriate rate…”.
The rate is 2% on every ringgit of CI from such profits [Part XXIII, Schedule 1, Income Tax Act 1967].
If the individual taxpayer has income from LLP distribution and income other than LLP distribution, the determination of the amount of CI from LLP distribution is based on the following formula:
A x C
B
Where:
- LLP distribution deemed as SI
- B is Aggregate income of the individual
- C is CI of the individual
The 2% tax is imposed on the CI from LLP distribution when the annual tax return is submitted by the resident individual (vide Form B or BE) or the NR individual (vide Form M).
The CI on the income from non-LLP distribution sources will continue to be subject to tax at the prevailing rate applicable to the individual under scale rates (for resident individuals) or fixed rate (of 30% for NR individuals).
2. Tax rates for unit holders who receive distributions of REIT and PTF
The tax rates for the distributions of REIT and PTF were prescribed in Part X of Schedule 1, Income Tax Act 1967 for a period of six years from YA 2020 to YA 2025 in the form of final WHT.
The rates were NOT extended by the Finance Act 2025. This means that w.e.f. YA 2026, the said WHT rates no longer applied.
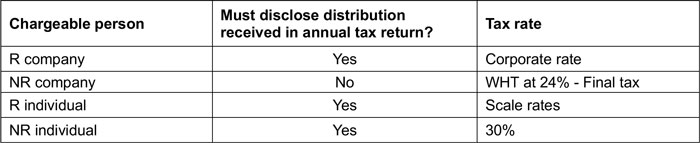
Practice Note 2 of 2026 was issued by IRB on 18 March 2026 to confirm the tax rates applicable to the unit holders who receive distributions from REIT or PTF, as follows:
Written by a member of the ATX-MYS examining team
